Personal Loan Interest Rate is one of the first numbers of borrower’s notice, but it should not be the only one they compare. Lenders may consider credit history, income, existing EMIs, requested amount, tenure and other risk factors before deciding the pricing applicable to an application.
India’s personal-credit market remains active. TransUnion CIBIL’s Credit Market Indicator – September 2026 reported that personal-loan origination value for the quarter ended June 2026 increased 34% year over year, while origination volume rose 27%. Understanding how loan pricing works is therefore increasingly relevant for borrowers.
Quick Answer: What Determines Your Loan Rate?
A Personal Loan Interest Rate can vary by borrower and lender. Credit profile, income, existing obligations, loan amount, repayment tenure and lender pricing policies can influence the rate.
The best comparison is not simply the lowest advertised number. Borrowers should also consider APR where applicable, processing fees, other charges, EMI, tenure and overall repayment cost before accepting an offer.
Key Facts
- Personal-loan origination value increased 34% year over year in the quarter ended June 2026. Source: TransUnion CIBIL
- Personal-loan origination volume increased 27% year over year during the same quarter. Source: TransUnion CIBIL
- CIBIL’s Personal Loan guidance states that rates can vary between borrowers and lenders.
- CIBIL identifies loan amount relative to income, tenure and credit profile among factors that can affect Personal Loan rates.
- RBI’s regulatory handbook notes that NBFC interest-rate models can consider cost of funds, margin and risk premium. Source: Reserve Bank of India
- RBI requires APR disclosure in the Key Facts Statement and loan agreement for applicable lending products.
What Is a Personal Loan Interest Rate?
A Personal Loan Interest Rate is the rate charged by a lender on the amount borrowed. A standard Personal Loan is generally unsecured, meaning the borrower typically does not pledge property as collateral for the facility. As a result, the lender can place significant weight on the applicant’s credit and financial profile when assessing the application.
The rate may be fixed or structured differently depending on the product and lender. RBI’s regulatory handbook on banking and financial-sector regulations notes that NBFC interest rates are deregulated and that their boards adopt interest-rate models that may consider factors including cost of funds, margin and risk premium.
This is why there is no single rate applicable to every borrower. A rate shown online may be indicative unless the lender expressly identifies it as the final applicable rate in the relevant loan documentation.
For product-specific information, explore Vindhya Finance’s Personal Loan service.
Personal Loan Interest Rate: What Factors Determine It?
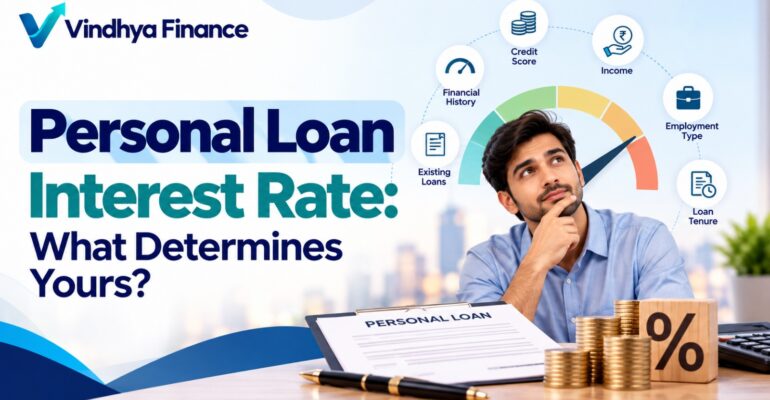
Your credit profile is important, but it is only one part of the pricing decision. CIBIL’s Personal Loan guidance identifies loan amount relative to income, tenure and credit profile among the factors that can affect Personal Loan rates.
Income and repayment capacity: Lenders may consider whether your income can support the proposed EMI alongside existing financial obligations.
Credit history: A consistent repayment record can support a stronger credit profile, while missed or delayed payments may affect the assessment.
Existing EMIs: Current loans reduce the amount of income available for another monthly repayment.
Loan amount: The amount requested relative to income and existing obligations can influence the lender’s risk assessment.
Loan tenure: The selected repayment period affects EMI and total interest and may also form part of pricing considerations.
Lender policy: Banks and NBFCs can use different risk models, pricing frameworks and customer segments.
As a result, two borrowers with similar salaries can receive different loan offers because their credit histories, liabilities, requested amounts, tenure or other profile factors may differ.
CIBIL Score and Personal Loan Pricing
Your CIBIL Score summarises important elements of your credit history, while your complete credit report provides more detail about borrowing and repayment behaviour. For unsecured borrowing, that information can be particularly relevant because the lender generally does not have property collateral supporting the loan.
Before applying, review your credit report for inaccurate or unfamiliar entries. Check your repayment history, outstanding balances and active accounts. If you find an error, raise it through the appropriate correction process before making a major borrowing decision.
CIBIL’s Personal Loan guidance explains that Personal Loan rates can vary from one borrower to another and identifies the credit profile, loan amount relative to income and tenure as important factors affecting the rate.
A stronger credit profile does not guarantee approval or a particular rate. The final pricing remains subject to the lender’s assessment and applicable terms.
Already researching eligibility? Read Vindhya Finance’s Personal Loan Eligibility guide.
Personal Loan Rates in India: Compare the Total Cost
A lower advertised rate does not automatically mean a lower-cost loan. The actual financial commitment can also depend on processing fees, other applicable charges, tenure and repayment conditions.
For applicable digital-lending products, RBI’s guidance on floating-rate EMI-based personal loans and related disclosures states that the Annual Percentage Rate (APR) is to be disclosed in the Key Facts Statement and loan agreement.
APR can therefore provide a broader view of the annualised cost of credit than the headline interest rate alone.
| What to Compare | Why It Matters |
| Interest Rate | Determines the interest component of borrowing |
| APR | Helps assess broader annualised credit cost, where applicable |
| Processing Fee | Adds to the cost of obtaining credit |
| EMI | Determines the regular repayment obligation |
| Tenure | Affects EMI and total interest |
| Prepayment Terms | Important if you plan to repay early |
| Penal Charges | Relevant when an EMI is delayed |
Before accepting an offer, read the lender’s Key Facts Statement and loan agreement carefully. Compare offers using equivalent loan amounts and tenures instead of comparing headline rates in isolation.
How Can You Prepare for a Better Personal Loan Offer?
You cannot guarantee a lower rate, but you can make your application more financially prepared and compare available offers more effectively.
- Check your credit report before applying. Understand your repayment history and outstanding obligations.
- Maintain timely repayments. Consistent repayment behaviour can support a healthier credit profile.
- Keep income documents accurate. Ensure salary, employment or business information is consistent across your application and supporting records.
- Choose a realistic loan amount. Borrow according to your repayment capacity rather than simply targeting the highest amount available.
- Compare the total cost. Look beyond the interest rate and consider APR, fees, tenure and repayment obligations.
- Review the lender’s disclosures. Understand the KFS, loan agreement and applicable charges before accepting an offer.
- Avoid unsupported promises. Claims such as “lowest rate” or “guaranteed approval” should not be treated as universal outcomes.
Vindhya Finance is a loan assistance service and does not independently sanction or disburse loans. Loan approval, interest rate, loan amount, tenure, applicable charges and disbursal are determined solely by the respective lender based on its eligibility criteria, credit assessment and policies. Corrections
Ready to Explore Your Options?
Start by understanding your requirement, eligibility and the applicable loan terms.
Explore Personal Loan Assistance with Vindhya Finance
Frequently Asked Questions
What are Personal Loan Rates in India based on?
Personal Loan Rates in India can depend on the borrower’s credit profile, income, existing obligations, loan amount, tenure and the lender’s pricing and risk policies. Exact rates vary by lender and applicant.
Does Personal Loan Pricing depend on CIBIL Score?
It can. A lender may consider the borrower’s credit profile when assessing unsecured credit, along with income, existing obligations and other relevant application information.
Can two borrowers get different Personal Loan Interest Rates?
Yes. Borrowers with similar incomes can receive different rates because their credit history, liabilities, requested loan amount, tenure and other risk characteristics may differ.
Is a lower Personal Loan Interest Rate always better?
Not necessarily. Borrowers should compare APR where applicable, processing fees, other charges, tenure, EMI and the overall repayment amount before choosing an offer.
Conclusion
Personal Loan Interest Rate is important, but it is only one part of a borrowing decision. Credit profile, income, existing EMIs, requested loan amount, tenure and lender pricing policies can all influence the offer a borrower receives.
Before applying, review your credit history, understand your repayment capacity and compare the complete cost of credit. Pay attention to APR, applicable fees, EMI, tenure and the Key Facts Statement rather than relying only on a headline rate.
When you’re ready to explore your options, visit Vindhya Finance Personal Loan assistance or contact the assistance team.