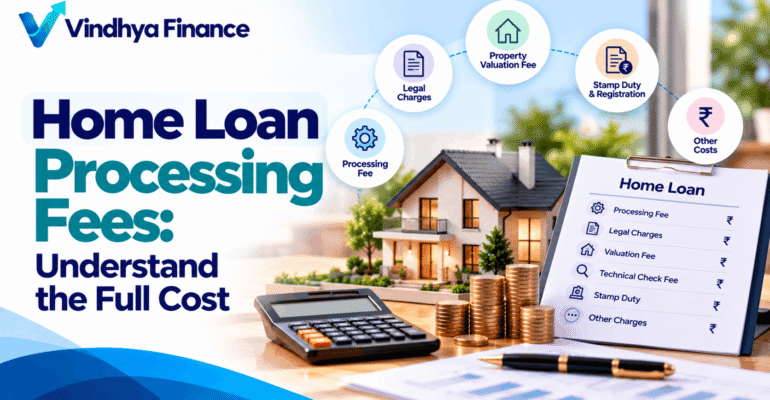
Home Loan Processing Fees are one part of the total cost of borrowing to buy, build or improve a home. The interest rate gets much of the attention, but application-related charges, property checks, documentation expenses and other applicable costs can also affect the money you need upfront.
Fees and charges differ by lender, property, loan structure and current offer. This guide explains common categories to check and the questions to ask before proceeding. Treat each item as something to verify in the lender’s written quotation and loan documents, not as a charge that every lender necessarily applies.
Quick Answer: What do home loan processing fees include?
Home Loan Processing Fees may be charged for handling an application. Other possible costs include legal or technical property assessment, documentation, mortgage-related expenses, statutory charges and applicable taxes. Ask the lender for a written breakdown and compare the total cost, not just the advertised interest rate.
Key Facts About Home Loan Processing Fees
- Processing fees and other charges vary by lender and offer.
- Some costs may be fixed, percentage-based, conditional or payable to a third party.
- Property legal and technical checks may be arranged by the lender or its appointed agency.
- Taxes may apply to particular fees or services.
- A promotional waiver may cover only specified charges and conditions.
- The lender’s Key Facts Statement and loan documents should be reviewed before acceptance.
What Do Home Loan Processing Fees Include?
A processing fee generally relates to the lender’s handling of a loan application. The precise services covered, amount, tax treatment and payment timing are determined by the lender’s policy and offer. Some lenders may advertise a fixed charge; others may calculate a charge using the requested loan amount, subject to their terms.
Processing fees should be distinguished from other expenses associated with the property or loan. A fee described as a legal, valuation or documentation charge may be separate from the main processing fee and may be payable to the lender or an appointed service provider.
Common categories to verify include:
- Processing/application fee: The charge, if any, for handling the loan request.
- Legal assessment: Review of relevant property documents or legal aspects, where arranged.
- Technical or valuation assessment: Assessment of the property under the lender’s process.
- Mortgage or security-related expenses: Costs associated with creating or recording security, where applicable.
- Statutory and documentation charges: Amounts that depend on the transaction, location and applicable requirements.
- Taxes: Applicable taxes on fees or services, as reflected in the relevant invoice or disclosure.
These are categories to verify, not a universal fee list. Some charges may not apply to a particular case, and the amount or responsible recipient may differ.
Home Loan Processing Fees and Other Charges: Comparison Table
| Cost category | What to check | Question to ask |
| Processing fee | Amount, calculation basis, tax and payment timing | Is the fee fixed or linked to the loan amount? |
| Legal assessment | Whether charged separately and who receives it | What work does this charge cover? |
| Technical/valuation fee | Whether an assessment is required and its cost | Is this a separate amount or part of another fee? |
| Mortgage/security costs | Applicable state/transaction requirements and paperwork | Which costs are payable and to whom? |
| Documentation/administrative fees | Purpose, amount and refund conditions, if any | Is this separate from the processing fee? |
| Insurance or optional products | Whether required, optional or separate from the loan | Can I review terms and costs separately? |
A comparison table helps you ask the same questions of each lender. Do not assume a charge is mandatory, optional or refundable from its name alone; ask for the written terms and confirm the conditions that apply to your case.
If you are still evaluating affordability and qualification factors, read our Home Loan Eligibility Guide.
What Affects the Total Cost of a Home Loan?
The total upfront cost depends on more than the headline processing fee. A lower fee may not make one offer less expensive overall if the rate, tenure, other charges or loan conditions differ.
- Loan amount and product: Some charges may be calculated in relation to the requested amount or product type.
- Property and transaction: The nature, location and documentation of the property can affect the checks or statutory expenses involved.
- Lender policy: Fees and the services they cover can differ between institutions.
- Promotional terms: A waiver may apply only to selected charges, loan amounts, customer groups or periods.
- Application outcome and refund conditions: Confirm what happens to fees if the application is withdrawn, declined or not completed.
Consider the full borrowing cost alongside the upfront amount. Interest, repayment tenure, the EMI, and other charges influence the overall cost over time. The amount shown in an estimate is not a final offer unless the lender explicitly identifies it as such.
For a broader framework for comparing rates, EMI, tenure and charges, read How to Choose the Right Loan.
How to Review and Compare Lender Charges
Before accepting a home loan offer:
- Ask each lender for a written and itemised schedule of fees and charges.
- Check whether taxes are included in quoted amounts or will be added separately.
- Identify which payments go to the lender and which may be payable to an appointed third party or government authority.
- Read the Key Facts Statement, sanction terms and related documents supplied for your application.
- Check any conditions attached to a fee waiver and whether the waiver affects one charge or several.
- Keep receipts, written quotations and communications so you can reconcile amounts later.
Avoid comparing offers using the processing fee alone. Compare the approved amount, interest-rate structure, expected EMI, tenure, APR where provided, applicable fees and repayment conditions together. Ask the lender to clarify any charge you do not understand before accepting the offer.
You can explore the service details on our Home Loan page or send your question through Contact Us.
Conclusion: Compare the Complete Home Loan Cost
Home Loan Processing Fees matter, but they are only one component of the total cost of financing a property. Ask for an itemised list of charges, check what each amount covers and compare the lender’s written terms before accepting a loan.
Vindhya Finance provides loan assistance and does not independently sanction or disburse loans. Loan approval, interest rate, loan amount, tenure, applicable charges and disbursal are determined solely by the respective bank, NBFC or housing finance company based on its assessment and policies.
FAQs About Home Loan Processing Fees
Are Home Loan Processing Fees the same for every lender?
No. The amount, calculation method, applicable taxes, payment timing and refund conditions may differ by lender, product and offer.
Are legal and technical charges included in the processing fee?
Not always. They may be separate charges or handled differently under a particular lender’s offer. Ask for an itemised written breakdown.
Can a home loan processing fee be refunded?
Refundability depends on the lender’s written terms and the circumstances. Confirm the policy before paying.
Should I choose a home loan with the lowest processing fee?
Not on that factor alone. Compare the interest-rate structure, tenure, EMI, other charges and contractual terms to understand the overall cost.
Related Vindhya Finance Pages
Home Loan | Home Loan Eligibility Guide | How to Choose the Right Loan | Contact Us
Important Disclosure: Vindhya Finance is a loan assistance service and does not independently sanction or disburse loans. Loan approval, interest rate, loan amount, tenure, applicable charges and disbursal are determined solely by the respective bank, NBFC or housing finance company based on its eligibility criteria, credit assessment and policies.