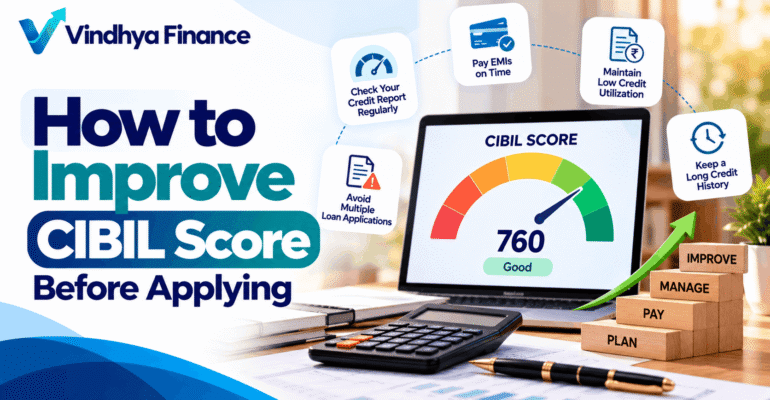
How to Improve CIBIL Score before applying for a personal loan, home loan or another form of credit starts with understanding the information in your credit report. Your score summarises parts of your credit history, while the underlying report shows accounts and enquiries that a lender may review as part of an application.
There is no instant or guaranteed method to raise a score by a fixed number. The most useful approach is to review your credit report, correct genuine errors, manage existing credit responsibly and give accurate information when applying. Lenders use their own eligibility criteria, so a particular score does not guarantee approval.
Quick Answer: How can you work toward a better CIBIL Score?
Pay EMIs and credit-card dues on time, keep credit-card balances manageable, review your credit report for errors, avoid unnecessary credit applications and maintain accurate account information. Improvements depend on your credit history and how updated information is reported.
Key Facts About Improving Your CIBIL Score
- A CIBIL Score is based on credit-history information; lenders may also review the underlying report.
- Payment history and outstanding balances are important parts of credit management.
- Incorrect account or payment information should be disputed through the appropriate process.
- Multiple applications in a short period may create additional credit enquiries.
- A score change is not immediate and cannot be guaranteed by a particular action.
- Lenders consider additional factors such as income, existing obligations and their own policy.
What Does CIBIL Score Mean?
A CIBIL Score is a numerical summary of information in a person’s credit history. It is useful, but it is not the whole credit profile. The credit report behind the score can contain details about loan and credit-card accounts, outstanding balances, payment status and enquiries.
When a lender reviews an application, it may consider the score along with income, employment or business stability, existing obligations, documentation and the requested loan amount. That is why a strong score can support an application but cannot by itself ensure sanction.
A sensible first step is to review the report before applying. Check whether accounts you have closed are shown correctly, balances look accurate, payments are recorded properly and enquiries correspond to applications you actually made.
For a broader overview of the financial factors that may affect approval, read our Personal Loan Eligibility Guide.
How to Improve CIBIL Score: Practical Steps
-
Pay EMIs and Credit-Card Dues on Time
Payment discipline is an important part of responsible credit management. Pay EMIs and card dues by their due dates. Set reminders or payment instructions only after confirming they are correctly configured, and keep sufficient balance to meet scheduled payments.
-
Manage Credit-Card Utilisation
Avoid keeping balances close to the available limit for extended periods. Do not treat a particular utilisation percentage as a guaranteed scoring formula. Instead, focus on managing borrowing within a realistic budget and paying obligations on time.
-
Review Your Credit Report Regularly
Check account status, balances, payment history and enquiries for information that appears inaccurate or unfamiliar. If an account is shown as open when you believe it has been closed, or a payment record seems incorrect, investigate it.
-
Raise Disputes for Genuine Errors
Follow the relevant credit information company’s process and retain reference numbers or correspondence. Do not assume every negative-looking entry is an error; compare it against your own records and contact the relevant institution if clarification is needed.
-
Avoid Unnecessary Credit Applications
Apply when you have reviewed the likely eligibility requirements rather than submitting multiple applications just to test approval. Unnecessary applications may lead to additional enquiries on your credit report.
-
Keep Account Information Current
If a lender has outdated or incorrect details, ask the lender about the process for correcting them.
-
Maintain Sustainable Borrowing Habits
Borrow only amounts you can repay and avoid taking fresh credit simply to try to improve a score.
These steps support responsible credit management, but they do not guarantee a particular score or timeline. The outcome depends on the details of your report, the type of issue and when the relevant lender or credit information company updates the record.
Habits That Can Harm Your Credit Profile
| Habit or issue | Why it may matter | Practical response |
| Missed or late payments | May be reflected in payment history | Prioritise dues and set up reliable reminders |
| High outstanding balances | May signal a heavy reliance on revolving credit | Reduce balances according to a realistic budget |
| Frequent applications | Can create multiple enquiries in the report | Apply selectively after checking requirements |
| Incorrect report data | May make the report inaccurate | Raise a documented dispute with the appropriate party |
| Unrecognised account | May indicate an error or possible misuse | Contact the lender and follow its investigation process |
| Over-borrowing | Can strain repayment capacity | Review the budget and existing obligations before borrowing |
Avoid shortcuts that promise a guaranteed score increase or ask you to misrepresent information. Accurate reporting and consistent repayment behaviour are more defensible than quick-fix claims.
If your next step is a home loan, our Home Loan Eligibility Guide explains other factors lenders may assess.
How Long Can It Take to Improve CIBIL Score?
There is no fixed timeline. A corrected reporting error may follow a different process from building a longer record of on-time payments or reducing outstanding balances. Credit records also depend on when lenders submit updates and when those updates are processed.
Rather than planning around a promised number of days, identify the specific issue in your report and take the action that addresses it. Recheck the report after the relevant institution has had time to process an update. Keep copies of dispute acknowledgements and any response you receive.
Before applying for a new loan, review your current income, recurring obligations and the amount you need. A stronger credit profile can help, but it should form part of a wider affordability check.
When you are ready to explore loan assistance, review the relevant Personal Loan or Home Loan page, or contact us through Vindhya Finance Contact Us.
Conclusion: Build a Consistent Credit Record
To improve your CIBIL Score, focus on the parts of your credit profile you can responsibly manage: payment discipline, outstanding balances, accurate reporting and selective applications. Review your report, investigate genuine discrepancies and allow time for accurate information to be updated. If you are looking for how to improve CIBIL Score before applying, use these steps as a plan for responsible credit management rather than a promise of a particular score.
A score is one input in lending decisions, not a promise of approval. Vindhya Finance provides loan assistance; the relevant lender determines eligibility and the final loan terms under its policies.
FAQs About Improving CIBIL Score
How can I improve my CIBIL Score?
Pay dues on time, manage outstanding balances, review the report for errors, dispute inaccuracies and avoid unnecessary credit applications. No method guarantees a specific score increase.
Can my CIBIL Score improve overnight?
You should not expect an overnight change. The timing depends on the underlying issue and when corrected or updated information is reported and processed.
Does checking my own credit report reduce my score?
Checking your own report for review is different from making a formal credit application. Review the terms of the service you use and distinguish a personal check from a lender enquiry.
Will a high CIBIL Score guarantee loan approval?
No. Lenders may also consider income, existing EMIs, employment or business profile, documents, loan amount and internal eligibility criteria.
Related Vindhya Finance Pages
Personal Loan Eligibility Guide | Home Loan Eligibility Guide | Personal Loan | Home Loan | Contact Us
Important Disclosure: Vindhya Finance is a loan assistance service and does not independently sanction or disburse loans. Loan approval, interest rate, loan amount, tenure, applicable charges and disbursal are determined solely by the respective bank, NBFC or housing finance company based on its eligibility criteria, credit assessment and policies.