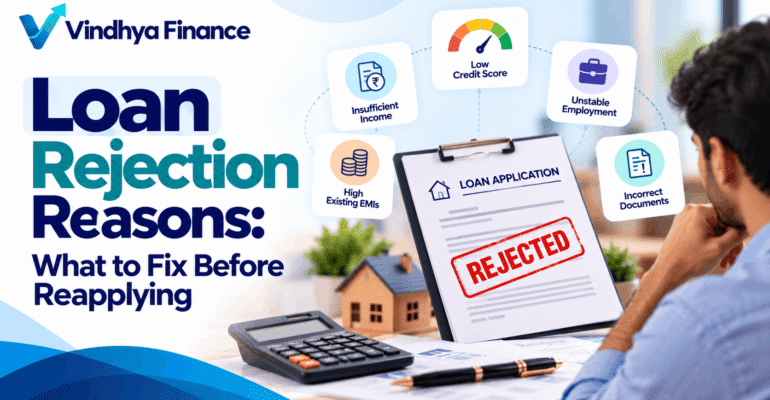
Loan Rejection Reasons can range from incomplete documents to a mismatch between the requested loan and the applicant’s income, credit profile or existing obligations. A rejection does not always mean that every lender will reach the same decision, but repeating the same application without understanding the issue can lead to avoidable enquiries and frustration.
The most useful next step is to identify what the lender assessed and what can be corrected. Lenders use different eligibility rules, and Vindhya Finance does not make the final lending decision. The relevant bank, NBFC or housing finance company evaluates the application under its own policy.
Quick Answer: Why do loan applications get rejected?
Common Loan Rejection Reasons include insufficient or unstable documented income, high existing repayment obligations, credit-history concerns, incomplete or inconsistent documents, limited employment or business history, and a requested amount that does not fit the lender’s criteria. Ask the lender for the reason and address it before applying again.
Key Facts About Loan Rejection Reasons
- A good credit score does not guarantee loan approval.
- Lenders may assess income, employment, obligations, documentation and requested loan amount.
- Missing or inconsistent information can lead to delays or rejection.
- Submitting multiple applications without a plan may create extra enquiries.
- The reason and available next steps depend on the lender and application.
- Do not assume a rejection by one lender means all lenders will decide the same way.
Common Loan Rejection Reasons
The following are possible explanations for a declined application.
| Possible reason | What it can mean | What to review |
| Income does not meet criteria | Documented income may not support the requested loan | Verify income records and reconsider the amount or EMI |
| High existing obligations | Current EMIs and other fixed commitments may leave limited repayment room | List current obligations and review affordability |
| Credit-history concerns | Late payments, high balances, settled accounts or other report details may matter | Check the credit report and clarify genuine errors |
| Incomplete documents | Required information may be missing or unreadable | Follow the specific document checklist and upload clear records |
| Information mismatch | Names, address, employer or income details may conflict | Correct errors and explain legitimate differences |
| Employment/business profile | Work history or income variability may not meet lender policy | Provide accurate supporting information if requested |
| Loan amount or property concerns | The request may not fit lender criteria or property requirements | Ask what part of the request did not meet the criteria |
These are possible explanations, not a diagnosis of any individual case. Only the lender can clarify the reason applicable to a particular application where it is able and required to do so.
Our Personal Loan Eligibility Guide and Home Loan Eligibility Guide describe common factors that may matter for each product.
What to Do After a Loan Application Is Rejected
A rejected application can be frustrating, but the next step should be to understand what happened rather than immediately submitting another application.
- Read the lender’s communication. Contact the lender if the reason is unclear or further information is available.
- Review your application. Compare the details entered with the documents submitted. Look for omissions, conflicting details or incorrect information.
- Check your credit report. If credit history may have played a role, investigate unfamiliar accounts, incorrect payment status or outdated balances.
- Review current income and obligations. Calculate the impact of another EMI on your monthly budget.
- Correct the specific issue. Address the problem where possible before making another formal application.
- Keep records. Save lender communications, dispute references and updated documents.
Do not change accurate information just to fit an eligibility expectation. If your income varies or you changed jobs recently, explain the situation truthfully and ask what supporting documents the lender accepts. False, altered or misleading records can create more serious problems than a straightforward decline.
Also distinguish a rejected application from a request for more information or a pending application. Check the exact status with the relevant institution rather than assuming the process has ended.
How to Prepare Before Reapplying
A new application is more useful when something material has changed or an error has been corrected. Before reapplying, check the following:
- Affordability: Understand the proposed EMI and total repayment commitment.
- Credit report: Address genuine reporting errors and manage overdue balances.
- Documentation: Collect complete and current documents required for the new application.
- Application amount: Consider whether a different loan amount or tenure is more appropriate, subject to lender terms.
- Lender fit: Review the lender’s published eligibility requirements where available.
- Timing: Avoid sending multiple applications just to test which one might approve.
There is no universal waiting period that guarantees a better outcome. Timing depends on the reason for rejection, any changes in your circumstances and the lender’s policy. For example, replacing an unreadable document may be a different situation from building a more stable repayment record.
If you are comparing products before making the next move, use our guide on How to Choose the Right Loan.
Loan Rejection Reasons and Practical Next Steps
The goal is to address the actual issue rather than make a different application without new information. The examples below show how the next step can vary.
| If the concern is… | A sensible next step |
| Missing or unreadable documents | Ask for the exact missing items and resubmit complete, legible records through the verified process. |
| An apparent credit-report error | Contact the relevant lender or credit information company and follow the correction/dispute process. |
| High recurring obligations | Review your budget and avoid taking on another EMI that leaves insufficient room for essential expenses. |
| Income or employment evidence | Ask which accepted documents can demonstrate your current circumstances. |
| Loan amount or property assessment | Ask the lender which criterion was not met and whether any alternative structure is available under its policy. |
These steps do not guarantee approval. They can, however, help make the next decision more informed and reduce avoidable repetition.
When you need help exploring a relevant loan-assistance enquiry, visit the Personal Loan or Home Loan page, or contact Vindhya Finance.
Conclusion: Fix the Cause Before Reapplying
Loan Rejection Reasons are best handled one at a time. Understand the lender’s explanation, check the accuracy of your documents and credit information, review affordability and prepare a complete application before deciding whether to reapply.
Vindhya Finance is a loan assistance service and does not independently sanction or disburse loans. Approval, loan amount, interest rate, tenure, charges and disbursal are determined by the respective lender after its assessment.
FAQs About Loan Rejection Reasons
Why was my loan rejected despite a good CIBIL Score?
A score is only one factor. Income, existing EMIs, employment or business profile, documentation, requested amount and lender-specific criteria may also affect the decision.
Should I immediately apply to another lender?
First understand the reason for rejection and check whether your circumstances or documents need correction. Multiple applications without a clear plan may create additional enquiries.
How long should I wait before applying again?
There is no universal waiting period. It depends on why the application was declined, what can be corrected and the criteria of the lender you approach.
Can Vindhya Finance guarantee approval after rejection?
No. Vindhya Finance provides loan assistance and does not independently sanction or disburse loans. The relevant lender makes the final decision.
Related Vindhya Finance Pages
Personal Loan Eligibility Guide | Home Loan Eligibility Guide | How to Choose the Right Loan | Personal Loan | Home Loan | Contact Us
Important Disclosure: Vindhya Finance is a loan assistance service and does not independently sanction or disburse loans. Loan approval, interest rate, loan amount, tenure, applicable charges and disbursal are determined solely by the respective bank, NBFC or housing finance company based on its eligibility criteria, credit assessment and policies.