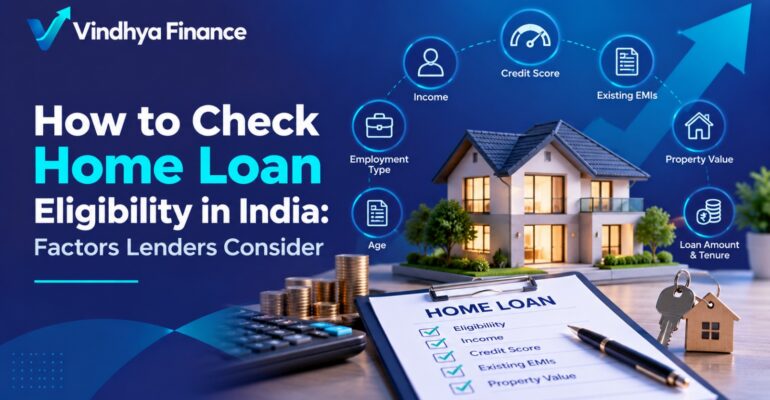
Home Loan Eligibility is one of the first things you should understand before planning your home purchase. A property may fit your budget, but the amount you can potentially borrow depends on factors such as income, existing EMIs, credit history, repayment capacity, employment profile, loan tenure and property details.
India’s housing-credit market has continued to expand. According to the National Housing Bank’s Report on Trend & Progress of Housing in India, individual housing loans outstanding across HFCs, public-sector banks and private-sector banks reached ₹36.70 lakh crore as of September 30, 2025, with 9.43% year-over-year growth.
Understanding your Home Loan Eligibility in India before applying can help you set a realistic property budget, prepare your documents and approach lenders with greater clarity.
What Is Home Loan Eligibility?
Home Loan Eligibility refers to the level of housing finance a lender may consider for an applicant after assessing their financial profile, repayment capacity and, where applicable, the property being financed.
There is no single formula that applies to every borrower. Different lenders may use different assessment criteria, while your income, liabilities, credit profile, age and property information can affect the outcome.
Common factors include:
- Monthly and annual income
- Existing loan EMIs
- Credit history and score
- Age
- Employment or business stability
- Requested loan amount
- Repayment tenure
- Property value and documentation
According to CIBIL’s home-loan guidance, lenders may consider factors such as credit history, income, employment status and property-related information when evaluating a Home Loan application.
Home Loan Eligibility Criteria in India
Understanding the major Home Loan Eligibility Criteria can help you prepare before submitting an application.
| Factor | Why It Matters |
| Income | Helps assess your repayment capacity |
| Existing EMIs | Shows your current debt obligations |
| Credit History | Reflects previous repayment behaviour |
| Age | Can influence available loan tenure |
| Employment/Business Profile | Helps assess income stability |
| Loan Amount | Should align with repayment capacity |
| Loan Tenure | Affects EMI and total repayment |
| Property Details | Relevant to property-backed financing |
For example, two applicants earning the same monthly income may have different Home Loan Eligibility if one already has substantial monthly financial obligations.
How to Check Home Loan Eligibility Before Applying
Before submitting a Home Loan application, review your overall financial position.
- Assess Your Income
Consider income that can be consistently documented. Salaried applicants may provide salary-related records, while self-employed applicants may need business and tax documentation.
- Review Existing EMIs
Add your current monthly loan repayments. This helps you understand how much of your income is already committed to debt.
- Check Your Credit Profile
Review your credit report for repayment history, outstanding accounts and possible inaccuracies. CIBIL’s consumer guidance identifies credit history and score as important considerations in housing finance.
- Decide the Loan Amount You Need
Start with your actual financing requirement instead of automatically targeting the maximum amount you may qualify for.
- Consider the Property Cost
The property’s value, your available down payment and lender-specific financing policies all influence the overall borrowing requirement.
A Home Loan Eligibility Calculator can provide an initial estimate, but the result should be treated as indicative. The lender’s final assessment may differ.
Ready to explore your options?
Check Home Loan Eligibility with Vindhya Finance
Factors Affecting Home Loan Eligibility
Income and Repayment Capacity
Income is one of the most important elements considered during a Home Loan assessment. Lenders generally need to understand whether you can manage the proposed EMI alongside your existing obligations and regular expenses.
A higher income can support greater borrowing capacity, but it does not automatically mean a higher eligible loan amount.
Credit Score and Credit History
Your credit history provides information about your previous borrowing and repayment behaviour. A consistent repayment record can support a stronger credit profile, while missed or delayed payments may influence how an application is assessed.
Before applying, review your credit report and address any inaccuracies you find.
Existing EMIs and Financial Obligations
Your current loans and monthly repayments can reduce the portion of your income available for a new Home Loan EMI.
This is why Home Loan Eligibility should be considered in relation to your complete financial profile rather than your salary alone.
Age and Loan Tenure
Age can influence the repayment period available under lender policies. A longer tenure may reduce your monthly EMI, but it can also increase the total interest paid over the loan period.
Employment or Business Stability
Lenders may consider employment continuity or stable business income when assessing repayment capacity. The exact requirements can vary depending on the applicant and lender.
Property Value and Documentation
Property-related factors can also influence housing finance. These may include the property’s legal title, valuation, location and supporting documents.
CIBIL’s home-loan guidance also highlights property-related information as part of the lender’s assessment process.
Home Loan Eligibility for Salaried vs Self-Employed Applicants
Salaried and self-employed applicants can both seek Home Loans, but their supporting documentation may differ.
Salaried applicants may generally be asked for salary slips, Form 16, bank statements and employment-related information.
Self-employed applicants may need income-tax returns, financial statements, business information and bank statements.
The exact Home Loan Requirements depend on the lender and the individual application.
Explore Home Loan Assistance from Vindhya Finance
How to Improve Your Home Loan Eligibility
There is no guaranteed way to increase your eligibility, but better financial preparation can make your application more organised.
- Review your credit report before applying.
- Maintain timely repayment on existing loans and credit facilities.
- Manage existing debt where practically possible.
- Keep your income documents organised and up to date.
- Choose a loan amount that fits your repayment capacity.
- Compare tenure and EMI together, rather than focusing only on a lower EMI.
- Review property documentation before finalising the purchase.
The aim should not simply be to maximise borrowing. It should be to choose a repayment obligation that fits within your broader financial commitments.
What Documents Are Required for Home Loan Eligibility?
The exact documentation varies by lender, applicant profile and property.
Common Home Loan Requirements may include:
- Identity and address proof
- PAN and KYC documents
- Salary slips and employment records
- Form 16
- Income-tax returns
- Bank statements
- Financial statements for self-employed applicants
- Property and ownership documents
CIBIL’s Home Loan document guidance notes that documentation requirements can differ between lenders and applicants.
For a broader overview, explore Vindhya Finance’s Home Loan service page.
Frequently Asked Questions
How is Home Loan Eligibility calculated?
Lenders may assess factors including income, existing EMIs, credit profile, age, employment or business stability, loan amount, tenure and property details. The exact calculation varies by lender.
What factors affect Home Loan Eligibility?
Income, repayment capacity, existing financial obligations, credit history, age, employment profile, requested loan amount, tenure and property-related factors can all influence eligibility.
Can self-employed individuals get a Home Loan?
Yes. Self-employed individuals can apply for a Home Loan subject to the lender’s eligibility criteria and documentation requirements.
Does a higher salary guarantee higher Home Loan Eligibility?
No. Income is only one part of the assessment. Existing EMIs, credit history, age, tenure, property value and other lender-specific factors can also influence the final decision.
Conclusion
Understanding Home Loan Eligibility before applying can help you plan your home purchase more realistically and prepare for the application process.
Your income matters, but it is only one part of the assessment. Existing EMIs, credit history, age, employment or business stability, loan tenure, requested amount and property-related factors can also influence how a lender evaluates your application.
A Home Loan Eligibility Calculator can give you a useful starting point, but it should not be treated as a final approval or loan offer. The respective lender makes the final decision after reviewing your application and supporting documents.
Before moving ahead, review your credit profile, understand your repayment capacity and prepare the likely Home Loan Requirements.
Ready to take the next step?
Explore Home Loan Assistance from Vindhya Finance
2 thoughts on “How to Check Home Loan Eligibility in India: Factors Lenders Consider”