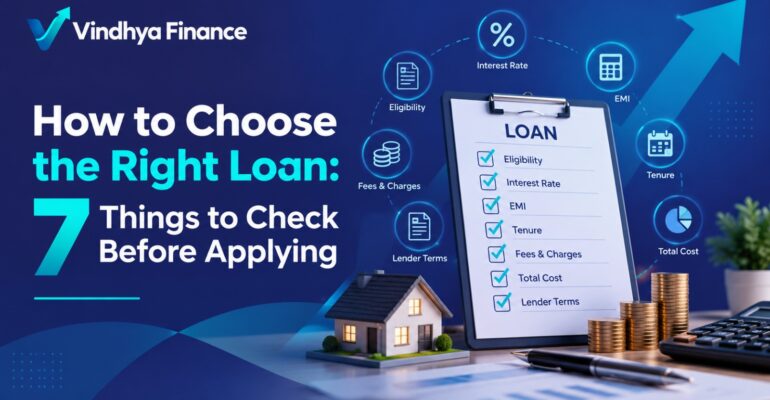
How to Choose the Right Loan is an important question to answer before you submit a loan application. A low advertised interest rate may look attractive, but it does not tell you the complete cost of borrowing. The right loan depends on your purpose, eligibility, repayment capacity, tenure, fees and the terms offered by the lender.
India’s formal credit ecosystem has expanded substantially. According to TransUnion CIBIL’s 2026 study on credit expansion in India, the share of India’s credit-eligible consumers who had accessed retail credit at least once increased from 35% in March 2017 to 74% in March 2026. The study also notes that India’s credit-eligible population increased from 79 crore to 89 crore consumers during the same period.
With more consumers participating in formal credit, knowing what to compare before borrowing has become increasingly important.
How to Choose the Right Loan Based on Your Financial Need
Start with why you need the money. The purpose of borrowing can determine which loan product is appropriate for your requirement.
For example, a Home Loan is designed around eligible housing-related financing, while a standard Personal Loan is generally unsecured and can be used for permitted personal requirements. Comparing the wrong products can make an otherwise useful financial decision unnecessarily complicated.
| Financial Requirement | Loan Type to Explore |
| Purchase a residential property | Home Loan |
| Construct a home | Home Loan |
| Major personal expense | Personal Loan |
| Medical or family-related requirement | Personal Loan |
| Certain home-related financing needs | Home Loan |
| Other eligible personal requirements | Personal Loan |
Explore Vindhya Finance’s Home Loan assistance or Personal Loan assistance based on your requirement.
How to Choose the Right Loan by Comparing the Total Cost
A common mistake is to compare loans using only the Loan Interest Rate.
Instead, look at the complete cost of borrowing. This may include:
- Interest rate
- Annual Percentage Rate (APR), where applicable
- Processing fee
- Other applicable charges
- Prepayment or foreclosure conditions
- Penal charges
- Other lender-specific costs
For digital lending, RBI requires the Annual Percentage Rate to be disclosed as the all-inclusive cost of credit and requires a Key Fact Statement (KFS) before execution of the loan contract for covered digital-lending products.
That means the advertised rate is only one part of the comparison.
Check Your Loan Eligibility Before Applying
Your Loan Eligibility should be considered before deciding how much you want to borrow.
Lenders can assess several factors, including:
- Income
- Existing EMIs
- Credit history
- Employment or business profile
- Age
- Requested loan amount
- Repayment tenure
- Property details for Home Loans
CIBIL explains that lenders use credit information when evaluating loan applications and that the final lending decision remains with the lender.
Checking your eligibility first can help you set a more realistic borrowing requirement instead of choosing a loan amount purely on the basis of what you would like to borrow.
Explore More
For product-specific considerations, read Vindhya Finance’s Home Loan guide and Personal Loan guide.
Compare Loan EMI With Your Existing Financial Commitments
Your Loan EMI should be considered alongside your current financial obligations.
Imagine a borrower earning ₹80,000 per month and already paying ₹15,000 toward existing loans. A proposed new EMI of ₹25,000 would bring total monthly loan repayments to ₹40,000.
That example does not establish whether the loan is affordable or whether a lender would approve it. It simply demonstrates why Loan Repayment Capacity matters.
Before applying, consider:
- Current EMIs
- Household expenses
- Existing credit-card obligations
- Emergency savings
- Proposed new EMI
- Future financial commitments
A lower EMI is not automatically a lower-cost loan. It may simply reflect a longer repayment period.
Compare Loan Tenure Carefully
Loan Tenure affects both your monthly repayment and the total interest paid.
In general, a longer tenure can spread repayment over more months and reduce the periodic EMI. However, paying interest for a longer period can increase the total amount repaid.
Consider the trade-off:
Shorter tenure: Higher EMI, potentially lower total interest.
Longer tenure: Lower EMI, potentially higher total interest.
The suitable tenure depends on your income, expenses, repayment capacity and financial objectives.
Review Loan Requirements and Documentation
Before applying, understand the Loan Requirements for the specific product and lender.
Depending on the loan type and applicant profile, common requirements may include:
- Identity and address proof
- PAN/KYC documents
- Income proof
- Bank statements
- Employment information
- Tax or financial records
- Property documents for Home Loans
CIBIL’s current loan guidance identifies credit reports, bank statements, KYC documents and income statements among common documentation categories, while noting that requirements can differ between lenders.
Having accurate and consistent documents ready can make the Loan Application process easier to navigate.
Don’t Overlook Loan Processing Fees and Other Charges
The Loan Processing Fee is only one charge you may encounter. Depending on the product and lender, there could also be other applicable charges.
Before accepting an offer, ask:
- What is the processing fee?
- Are there prepayment or foreclosure charges?
- What happens if an EMI is delayed?
- Are there other applicable service or documentation charges?
- What is the APR?
- What does the KFS disclose?
For covered digital-lending arrangements, RBI requires applicable costs to be disclosed upfront through the relevant documentation, including the KFS.
Understanding Loan Charges before accepting the facility can help you compare the actual cost rather than relying on promotional numbers.
Check the Lender and Read the Terms Before Accepting
The final step in understanding How to Choose the Right Loan is reviewing who is actually providing the credit and what you’re agreeing to.
Before accepting an offer, verify:
- Name of the lender
- Loan amount
- Interest rate
- APR, where applicable
- EMI
- Tenure
- Applicable charges
- Repayment schedule
- Prepayment conditions
- Other terms in the loan agreement/KFS
CIBIL explains that it maintains credit information used by lenders while the decision to lend remains solely with the lender.
Don’t proceed simply because an offer looks attractive at first glance. Read the relevant documents and understand the financial commitment.
How to Choose the Right Loan: A Simple Comparison Checklist
Before submitting your application, use this quick checklist:
| What to Check | Question to Ask |
| Purpose | Does this loan match my actual requirement? |
| Eligibility | Do I broadly meet the lender’s criteria? |
| Cost | Have I checked the interest rate, APR and fees? |
| EMI | Can I manage the repayment with existing commitments? |
| Tenure | Does the repayment period suit my finances? |
| Documents | Do I have the required information ready? |
| Terms | Have I read the KFS/loan agreement and relevant conditions? |
Need Help Understanding Your Options?
You don’t have to begin your borrowing journey by submitting an application immediately.
Start by understanding your requirement, checking eligibility and reviewing the relevant loan terms.
Talk to Vindhya Finance
Frequently Asked Questions
What should I consider when choosing a loan?
Consider the loan’s purpose, eligibility requirements, interest rate, APR where applicable, EMI, tenure, processing fee, other charges, documentation and repayment terms.
Should I choose a loan based only on the interest rate?
No. The interest rate is important, but you should also compare the overall cost, including applicable fees, APR, tenure, EMI and relevant prepayment or foreclosure terms.
How does loan tenure affect the cost?
A longer tenure can lower the periodic EMI, but it can also increase the total interest paid because the loan remains outstanding for a longer period.
What should I check before applying for a loan online?
Check the lender’s identity, eligibility criteria, loan amount, interest/APR, EMI, tenure, charges, documentation, privacy/consent terms and the applicable loan disclosures.
Conclusion
How to Choose the Right Loan starts with understanding your own financial requirement rather than focusing only on the amount you may be eligible to borrow.
Compare the loan purpose, eligibility, interest rate, APR, EMI, tenure, processing fee, other charges, documentation requirements and repayment capacity before applying. For digital loans, pay close attention to the lender’s disclosures and Key Fact Statement where applicable. RBI’s framework specifically emphasizes upfront disclosure of APR and the KFS for covered digital-lending products.
A good comparison is not about finding a universally “best” loan. It is about understanding the product, its total cost and its repayment obligations in the context of your own financial situation.
Ready to explore your options?
Explore Home Loan Assistance
Explore Personal Loan Assistance